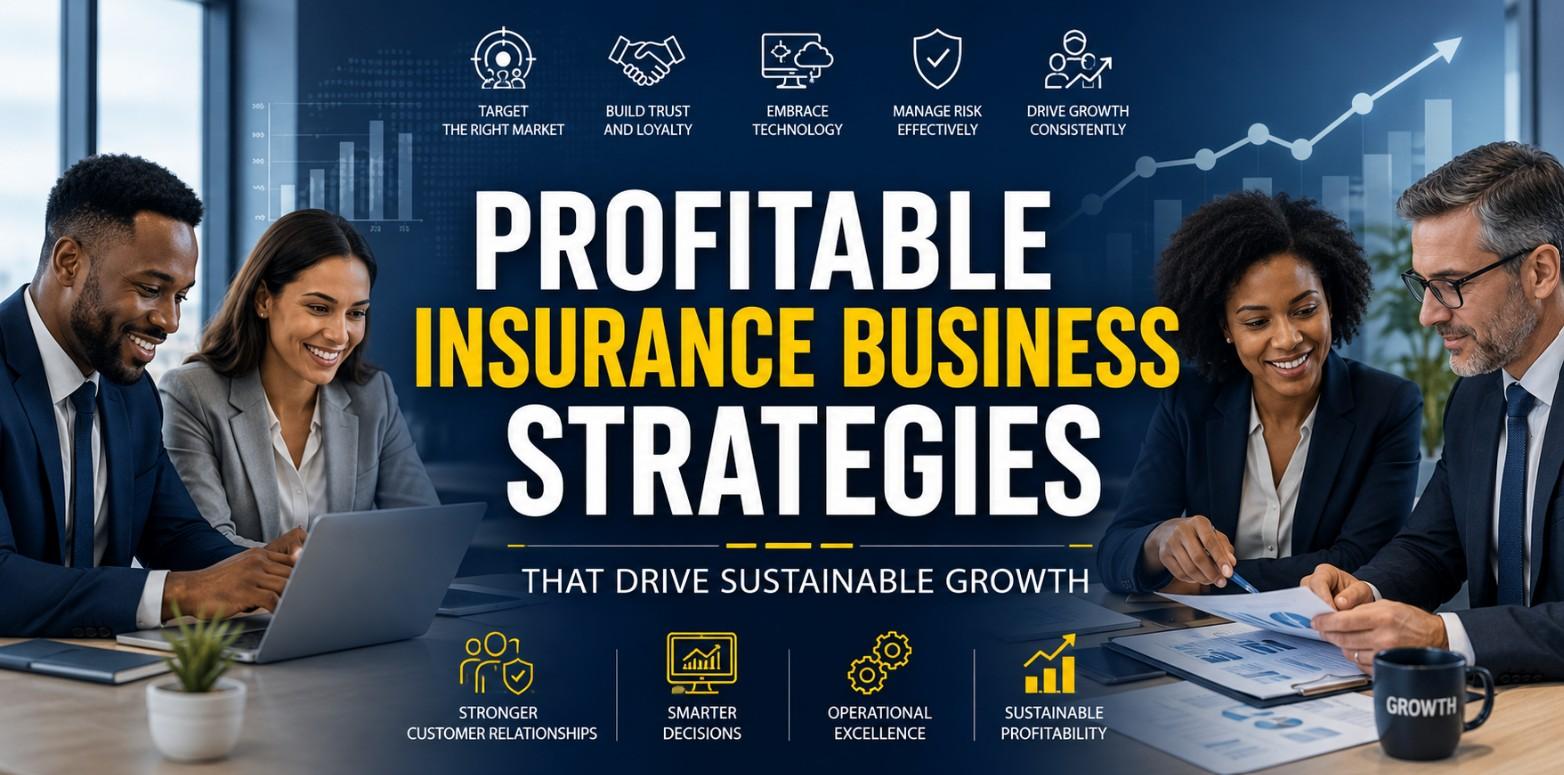
Profitable Insurance Business Strategies That Drive Sustainable Growth
The insurance industry continues to evolve as customer expectations, digital innovation, and market competition reshape the way businesses operate.
While demand for insurance products remains strong, long term profitability depends on much more than offering competitive policies. Insurance companies, agencies, and brokers need Profitable Insurance Business Strategies that improve customer relationships, streamline operations, and create consistent revenue opportunities.
Successful organizations understand that profitability is the result of careful planning, strong customer service, and continuous adaptation. Businesses that invest in modern technology, build trust with clients, and focus on operational excellence are better positioned to achieve sustainable growth.
Understand Your Target Market
Every profitable insurance business starts with a clear understanding of its ideal customers. Different industries, age groups, and business sectors have unique insurance requirements. Instead of trying to serve everyone, companies should identify specific market segments and develop solutions that address their needs.
Market research provides valuable insights into customer preferences, purchasing behavior, and emerging risks. These insights allow insurance professionals to create personalized offerings that increase customer satisfaction while improving conversion rates.
A focused approach also makes marketing efforts more efficient because businesses can communicate directly with the audience most likely to purchase their services.
Build Long Term Customer Relationships
Acquiring new customers is important, but retaining existing clients is often more profitable. Loyal customers are more likely to renew policies, purchase additional coverage, and recommend the business to others.
Strong relationships begin with excellent communication. Clients appreciate timely responses, clear explanations, and ongoing support throughout the policy lifecycle. Regular follow ups and policy reviews demonstrate commitment and help identify changing customer needs.
Businesses that consistently deliver value create trust, which becomes a significant competitive advantage in the insurance industry.
Embrace Digital Transformation
Technology has become a major driver of profitability in modern insurance businesses. Digital tools improve efficiency, reduce administrative work, and enhance the overall customer experience.
Automation can simplify routine processes such as policy management, claims processing, appointment scheduling, and document handling. Customer relationship management systems help organize client information and improve communication across teams.
Online quoting tools and digital applications also make it easier for customers to purchase insurance, creating a smoother experience while reducing operational costs.
Companies that embrace digital transformation are often able to serve more clients without significantly increasing overhead expenses.
Diversify Products and Services
Relying on a single insurance product may limit growth opportunities. Profitable businesses expand their offerings to meet a broader range of customer needs.
For example, commercial clients may require property insurance, liability coverage, employee benefits, and cyber protection. Individual customers may benefit from bundled solutions that combine multiple policies.
Cross selling relevant products increases revenue while strengthening customer relationships. Since clients already trust the provider, they are often more willing to consider additional coverage that delivers greater value and convenience.
Focus on Data Driven Decision Making
Data plays an essential role in improving profitability. Insurance businesses collect valuable information through customer interactions, claims history, policy renewals, and sales performance.
Analyzing this data helps identify trends, measure business performance, and uncover new opportunities. It also supports better pricing decisions, more accurate risk assessment, and improved customer targeting.
Business leaders who rely on measurable insights instead of assumptions are better equipped to make informed strategic decisions.
Invest in Employee Development
Employees represent one of the most valuable assets in any insurance business. Well trained professionals provide better customer service, build stronger client relationships, and contribute to higher sales performance.
Continuous learning helps employees stay informed about industry regulations, emerging risks, and new insurance products. Training programs also improve communication skills, negotiation techniques, and problem solving abilities.
A knowledgeable and motivated workforce creates a positive customer experience that contributes directly to business growth and profitability.
Strengthen Your Brand Reputation
Trust is the foundation of every successful insurance business. Customers want confidence that their provider will deliver reliable support when they need it most.
Building a strong reputation requires consistency across every customer interaction. Honest communication, transparent pricing, and efficient claims handling all contribute to a positive brand image.
Satisfied clients often become brand advocates who generate referrals through word of mouth. These referrals typically result in lower customer acquisition costs and higher quality business opportunities.
Improve Operational Efficiency
Profitable businesses regularly evaluate their internal processes to eliminate unnecessary costs and improve productivity.
Simple improvements can have a significant impact, including:
-
Reducing paperwork through digital documentation
-
Automating repetitive administrative tasks
-
Monitoring performance using clear business metrics
-
Improving collaboration between departments
Efficient operations allow teams to spend more time serving customers and developing new business opportunities instead of managing manual processes.
Prepare for Industry Changes
The insurance market is constantly influenced by economic conditions, regulatory updates, technological innovation, and changing customer expectations.
Businesses that remain flexible are better prepared to respond to new challenges. Regular strategic planning, ongoing market analysis, and investment in innovation help organizations remain competitive over the long term.
Rather than reacting to industry changes, successful insurance companies anticipate them and adjust their strategies accordingly.
Conclusion
Building a profitable insurance business requires a combination of customer focused service, operational excellence, and strategic planning. Companies that understand their market, embrace technology, invest in employee development, and strengthen customer relationships create a strong foundation for sustainable growth.
Profitability is not achieved through a single initiative. It comes from consistently improving every aspect of the business while adapting to changing market conditions. Insurance organizations that prioritize innovation, trust, and efficiency will be well positioned to succeed in an increasingly competitive marketplace.
Frequently Asked Questions
What is the most effective strategy for increasing insurance business profitability?
Improving customer retention, adopting digital technology, expanding service offerings, and making data driven decisions are among the most effective strategies for increasing long term profitability.
Why is customer retention important in the insurance industry?
Retaining existing customers is generally more cost effective than acquiring new ones. Loyal clients are more likely to renew policies, purchase additional coverage, and recommend the business to others.
How does technology improve insurance business performance?
Technology streamlines administrative tasks, enhances customer communication, speeds up claims processing, and reduces operational costs, allowing businesses to improve efficiency and profitability.
How can insurance companies stay competitive in a changing market?
Companies can remain competitive by understanding customer needs, investing in employee training, adopting modern technology, monitoring industry trends, and continuously improving their services.